In this article
Dwelling coverage (Coverage A) protects the physical structure of your home and everything permanently built into it. This is the foundation of your homeowners insurance: the part that pays to rebuild your house if it's damaged or destroyed.
Understanding what qualifies as dwelling coverage versus other types of coverage affects every claim you'll ever file.
What Does Dwelling Coverage Include?
Dwelling coverage protects your home's structure and permanently attached components. The test is simple: if removing it would damage the house or if it's built into the construction, it's typically Coverage A.
The structure itself: Walls, roof, foundation, floors, ceilings, and the home's frame. This includes structural elements like load-bearing walls, roof trusses, and the foundation system.
Built-in components: Kitchen cabinets, bathroom vanities, built-in bookshelves, hardwood flooring, tile work, and permanent fixtures. Trim, molding, and built-in entertainment centers also qualify.
Permanently attached fixtures: Light fixtures, ceiling fans, plumbing fixtures and built-in appliances like garbage disposals or even dishwashers and window treatments.
Attached structures: Attached garages, covered porches that share your home's foundation, and attached decks. The key is structural connection: if it's truly attached to your dwelling, it's usually Coverage A.
Does Dwelling Coverage Reach Under Your House?
One surprisingly common coverage dispute involves how far down the dwelling goes.
Most policies define the dwelling to include the foundation but exclude the land, soil, or earth. This distinction becomes critical when you have slab leaks, or underground plumbing failures.
Some policies specify coverage depths, like "soil within 6 inches of the foundation," while others are more vague or draw the line at the concrete itself. Check your policy's dwelling definition to understand where coverage stops and earth exclusions begin.
Understanding the estimating guidelines carriers use to price a settlement helps when carriers try to shift foundation repairs from dwelling coverage to excluded earth movement or soil issues.
What Does Dwelling Coverage Not Cover?
Standard dwelling coverage excludes several categories that require separate coverage or endorsements:
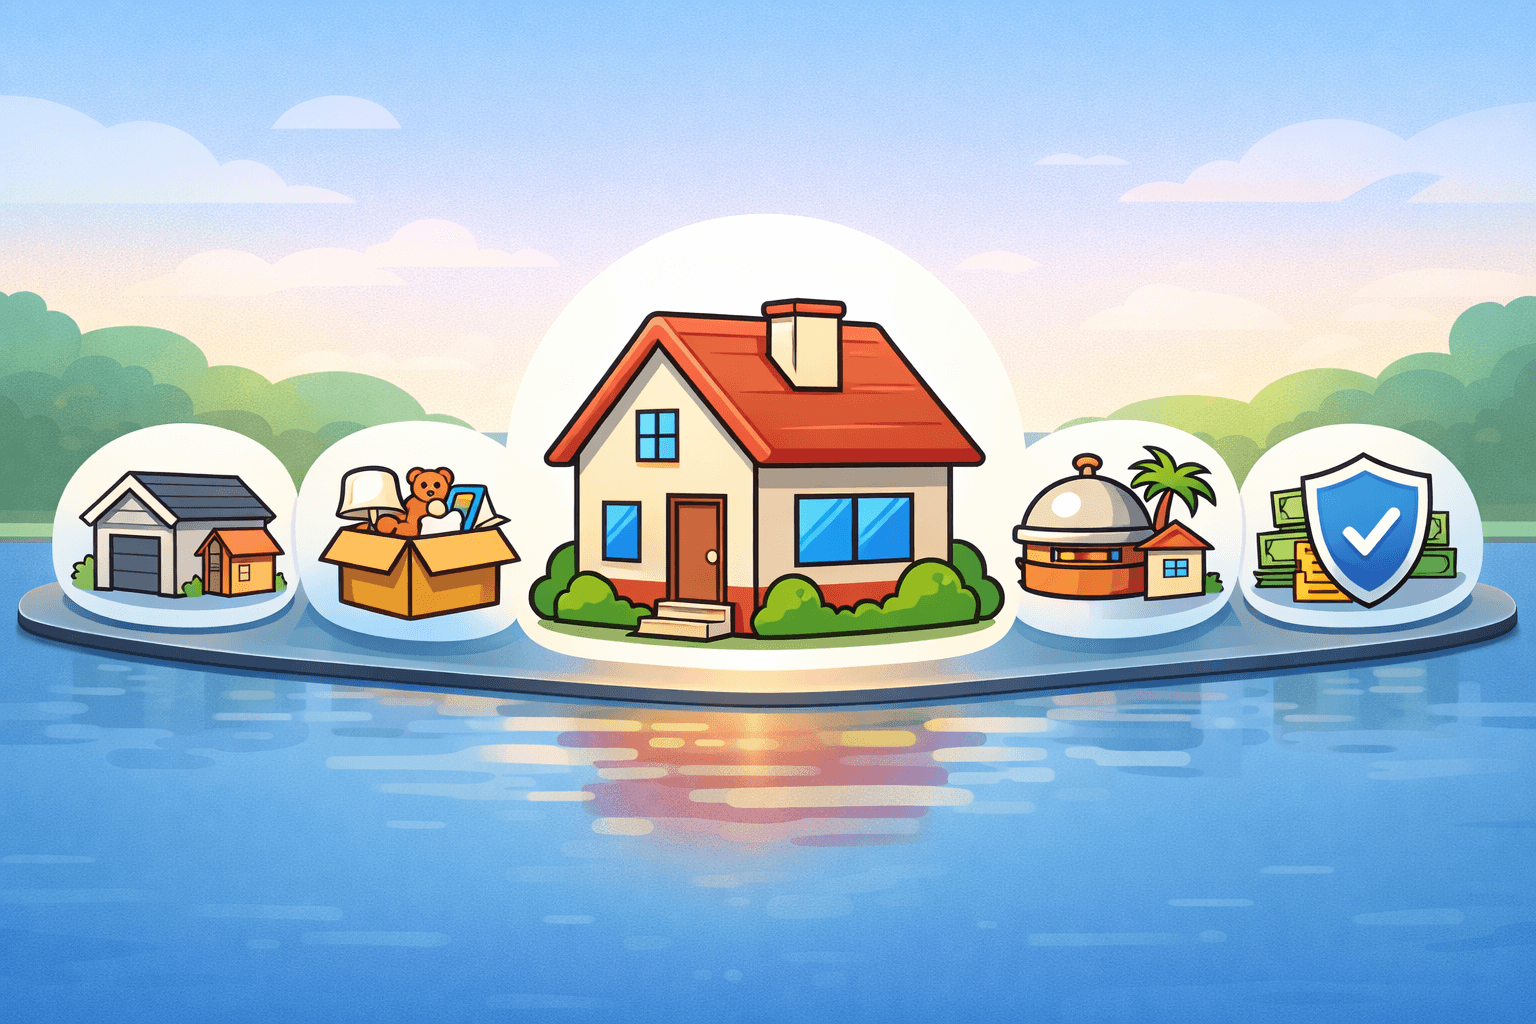
Detached structures like standalone garages, sheds, fences, and separate pool houses fall under Coverage B (Other Structures), not dwelling coverage. Even if these structures are expensive, they're covered under a separate limit.
Personal property (furniture, clothing, electronics, and moveable items) is covered under Coverage C (Personal Property), not dwelling coverage. This includes area rugs, artwork, and appliances that aren't built-in.
Flood and earthquake damage require separate policies entirely. Standard homeowners insurance excludes both, regardless of how the water enters your home or what causes the ground movement.
Gradual deterioration and maintenance issues aren't covered. Roof leaks from worn shingles, foundation problems from settling, and damage from deferred maintenance fall outside coverage.
Underground service lines connecting your home to utilities (water, sewer, gas, electrical) are typically excluded unless you add service line coverage. When these lines fail, excavation and replacement costs can be substantial.
How Much Dwelling Coverage Do You Need?
Your dwelling limit should reflect the cost to rebuild your home, not its market value. Market value includes the price of the land and moves with the real estate market, but your carrier only pays to rebuild the structure, not to rebuy the dirt it sits on. The dwelling limit is what it would cost to replace the home, and that figure may have nothing to do with what you paid for it.
A quick sanity check: divide your Coverage A limit by your home's finished square footage. If the result seems low compared to local construction costs, you may be underinsured; costs vary by region, but a substantial gap suggests your limit needs adjustment. For a real number, ask a local contractor for a rebuild estimate, or use a cost estimator; your insurer might even provide one. While you have the declarations page open, look for "replacement cost coverage," the wording that keeps depreciation from being subtracted from what you are paid.
Underinsurance is rarely discovered when the policy is written. It surfaces at claim time, when the rebuild estimate comes back above the Coverage A limit and the difference is yours to fund. Consider whether you've made improvements since purchasing your policy. Built-in improvements increase your coverage needs because they increase reconstruction costs.
If your carrier can't raise your base dwelling limit adequately, extended replacement cost or guaranteed replacement cost endorsements can help close coverage gaps. Extended replacement cost sits on top of your stated dwelling limit as a percentage overlay, commonly 20 to 50 percent depending on the endorsement, so a rebuild that runs past the limit still has somewhere to go. Guaranteed replacement cost goes further, but carriers usually condition it on your having insured the home to a set percentage of its rebuild cost at inception. Labor and material prices move too, and rising building costs can leave an adequate limit short a few years later.
What Else on Your Policy Needs to Be Sized?
Your belongings sit under Coverage C, and most policies set personal property coverage at around 50 to 70% of your dwelling coverage. That default might not be enough if you have high-value items: furniture, electronics, appliances, clothes, even that mountain of Legos. The cheapest way to find out where you stand is to walk through your home with your phone and record everything. A video inventory helps a lot during a claim, and yes, it counts as evidence.
Loss of use, also called Additional Living Expenses, pays if your home becomes unlivable during repairs, covering hotel stays, meals, and even laundromat runs. Make sure the limit is enough to cover a few months of alternate housing, especially if you're in a high-cost area.
Liability coverage handles a different kind of loss. If someone slips on your icy steps, or your dog mistakes a delivery guy for a chew toy, it has your back. Standard policies usually offer $100,000 to $300,000, but higher limits are smart if you have assets worth protecting, and an umbrella policy sits above your homeowners limit if you want broader protection.
Finally, size your policy for where you live. Floods and earthquakes are not covered by a standard homeowners policy, and depending on your location you might need additional policies or endorsements. If you've added a pool, finished a basement, or installed solar panels, your risk profile and your insurance needs might have changed.
Homeowners insurance isn't a set it and forget it deal. Renovations, inflation, and rising labor and material costs can leave you underinsured before you know it. Once a year, ask yourself whether you have made home improvements, whether the cost to rebuild has increased, whether you bought new furniture or expensive gear, and whether you are still covered for local risks. If the answer to any of those has changed, call your agent before a claims department has to tell you. Knowing what to ask your agent about coverage adequacy helps prevent expensive gaps from developing over time, and if you are not sure what your policy really covers, get a second opinion while you still have time to change it.